
Cash advance fees sting
The cash advance fee is $10 or 3% plus interest from day one. Standard for credit cards but worth knowing before you treat it like a debit card
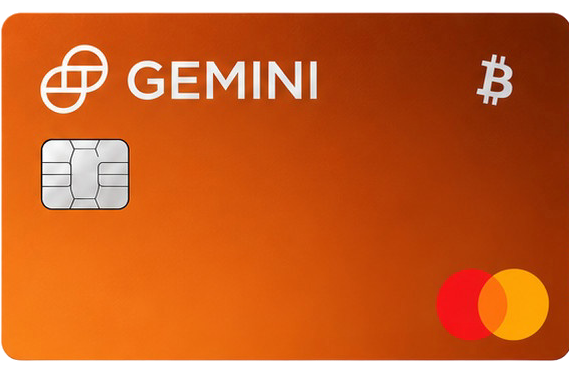
A credit Mastercard from Gemini that pays crypto rewards in real time.
Experience ratings
Average scores across key criteria.
User experiences verified by a moderator.
The cash advance fee is $10 or 3% plus interest from day one. Standard for credit cards but worth knowing before you treat it like a debit card

Hit the spend requirement in the first few months and got the $200 bonus in crypto. No annual fee, no FX fee, decent rewards. Good starter crypto card

This is the big one, it’s US only with a Social Security Number required. As a non US person I can’t even apply. Frustrating that the good one is region locked

Rewards deposit into a Gemini exchange account so you’re forced into their ecosystem whether you like it or not. Wanted just the card, got roped in

Finally a card that reports to the bureaus AND gives me crypto back. No coin sold at checkout, rewards just show up in my Gemini account. Been building credit while stacking BTC

This is a real credit card so applying dings your credit with a hard pull, and you need good credit to get approved. Not the easy signup some expect

They don’t publish a minimum but everyone I know needed good to excellent credit. Got denied with a fair score. Not accessible to everyone

You can pick which crypto to earn rewards in from a huge list. I rotate between BTC and ETH. Flexible in a way no other rewards card is. Solid
This isn’t a spend-your-crypto card, it’s a normal credit card that pays you in crypto. If you wanted to actually spend your holdings this isn’t it
Even within the US there are hoops, and if you move or have thin credit history approval is a maybe. Wish it were more straightforward
The crypto you earn counts as income when received AND triggers capital gains when you sell. Twice taxed. Turned my rewards into a tax season nightmare

Love that the crypto rewards hit instantly after each purchase and there’s no annual fee. Picked BTC as my reward and it’s been growing. Simple and effective

The purchase APR runs up to 28% variable and the penalty APR is 33%. If you don’t pay in full the interest wipes out any crypto reward instantly. Pay in full or don’t bother

Got the XRP edition and earn XRP on gas and rideshare. No FX fee is great for travel too. If you already like XRP it’s a no brainer

Earned rewards in a coin that then dropped and watched the value shrink before I could do anything. Unless you pick a stablecoin your cashback is a gamble
The ‘XRP edition’ has zero new features over the standard card, same rewards same fees, just an XRP logo. Pure marketing. Don’t expect anything extra
The top rates only apply to specific categories like gas and dining, everything else is 1%. The 4% headline is narrow. Read the categories
Gemini Credit Card is issued jointly by the Gemini exchange, Mastercard and WebBank. Its calling card is real-time crypto rewards that land in your Gemini account automatically.
There is no annual fee, which keeps the card competitive among US crypto credit cards. Once issued it works in mobile wallets, and holders get Mastercard premium benefits, including partner offers from the likes of DoorDash, HelloFresh and Lyft plus identity theft protection.
It is a credit Mastercard linked to your balance in the service. At checkout the crypto is converted into fiat and the transaction is routed through the Mastercard network, so the card works anywhere that payment system is accepted.
The stated coverage is United States. The exact country list and local restrictions are set by the issuer, so check the terms for your country of residence before applying.
Yes, in most cases you need to register and pass KYC with an ID document. Some issuers also ask you to confirm a residential address in a supported region.
The baseline terms are: APR 17–30% depending on credit history; no annual fee; late payment fees may apply. On top of that, factor in the conversion rate, ATM fees and any charges from the payment partner — the issuer always publishes the current pricing.
In most cases yes: the card can be added to a mobile wallet for contactless payments. Availability depends on your country and the payment partner's rules.