
The cashback is okay, but everything else isn’t that great.
Overall, I liked the cashback, but it’s really bad that the payment doesn’t always go through. In many stores and services, it just doesn’t work.
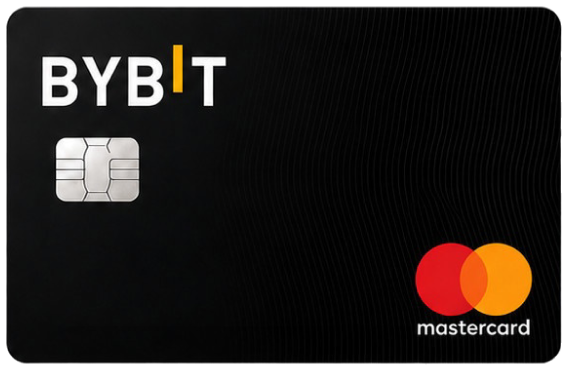
A debit Mastercard from Bybit that spends straight from your exchange balance, with promo cashback.
Experience ratings
Average scores across key criteria.
User experiences verified by a moderator.
Overall, I liked the cashback, but it’s really bad that the payment doesn’t always go through. In many stores and services, it just doesn’t work.
The biggest disappointment was not the idea of the Bybit Card itself, but how it behaves in practice. The card can be blocked by the risk system during a regular payment, after which you have to unlock it manually. But even after unlocking, the problem can happen again on the next payment attempt. As a result, you can’t be sure that the card will work exactly when you need it. The situation with support looks even worse: instead of a real solution, you get standard instructions to check the card status and try the operation again. It turns into a vicious circle – the card gets blocked, you unlock it, the payment gets blocked again, and support basically repeats the same thing. For a payment card, this is a critical flaw. I definitely wouldn’t use it as my main card, and even less would I keep significant amounts on it.
On paper, the Bybit card looks very attractive: cryptocurrency, regular payments, cashback, physical and virtual cards. But when you actually start using it, too many nuances appear. Transactions can be declined due to insufficient purchasing power, limits, or card blocking, and the terms themselves depend on the region. The fee system is particularly annoying. Even if there is no monthly fee, that doesn’t mean using it is free: depending on the region and the transaction, fees may apply for cryptocurrency conversion, currency exchange, or cash withdrawals. As a result, you constantly have to think about which balance you’re paying from, what currency the transaction is in, what your limit is, and whether the risk system will kick in. For me, this is not the level of predictability you expect from a payment card. If you can’t calmly pay with the card in a store without fear of getting blocked or declined, all the extra features and cashback don’t really matter anymore.

Good afternoon. I have been using the wallet for 1 month. At first, everything was fine while the amounts were small. Buying USDT in P2P is convenient and fast. But when an amount of 3990 USDT was credited to the wallet, the funds were blocked. Support responds with template answers. I have been waiting for the crediting for 7 days. So far, there is no credit. I will inform additionally as soon as the funds are credited.
Bybit Card is issued in partnership with UK payment infrastructure provider Moorwand, which operates under a Mastercard licence. The card is tied to your exchange balance and converts crypto into fiat at the moment of the transaction, and you choose which asset the funds come from.
The card comes in both virtual and physical form across most supported regions and works with Apple Pay and Google Pay depending on the country. New users get promotional terms with boosted cashback and a welcome bonus, while the standard reward rate depends on account tier and region.
It is a debit Mastercard (virtual and physical) linked to your balance in the service. At checkout the crypto is converted into fiat and the transaction is routed through the Mastercard network, so the card works anywhere that payment system is accepted.
The stated coverage is EEA countries, United Kingdom, Argentina, Brazil, AIFC (Kazakhstan), Australia. The exact country list and local restrictions are set by the issuer, so check the terms for your country of residence before applying.
Yes, in most cases you need to register and pass KYC with an ID document. Some issuers also ask you to confirm a residential address in a supported region.
The baseline terms are: 0% on payments in local currency; 0.9% crypto conversion; 1% FX fee; 2% ATM withdrawals; a free monthly withdrawal limit applies. On top of that, factor in the conversion rate, ATM fees and any charges from the payment partner — the issuer always publishes the current pricing.
In most cases yes: the card can be added to a mobile wallet for contactless payments. Availability depends on your country and the payment partner's rules.